
MAJORITY: Mobile banking
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
MAJORITY: Mobile banking - Screenshots
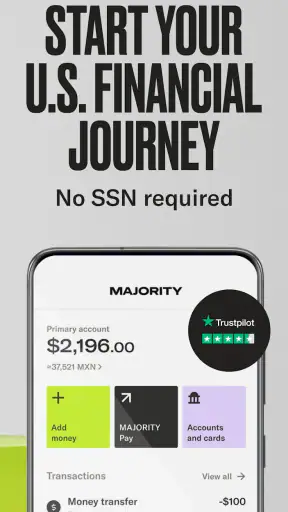
Pros
- Simple mobile banking tools for checking balances and managing money.
- Useful spending insights can help users monitor everyday finances.
- Mobile access makes banking convenient while traveling or away from a branch.
- Straightforward interface is suitable for users who prefer uncomplicated banking apps.
- Push notifications can help users stay informed about account activity.
Cons
- Available features may depend on your country and Majority account eligibility.
- Some services may involve fees that are not immediately obvious to new users.
- Customer support response times could vary during busy periods.
- Users may need identity verification before accessing key banking features.
- A mobile-only service may be inconvenient for people who prefer branch banking.
MAJORITY: Mobile banking - Description
- App Name
- MAJORITY: Mobile banking
- Package Name
- com.majority.android
- Developer
- MAJORITY USA, LLC
- Category
- Finance
- Last Updated
- Apr 26, 2019
- Version
- 5.14.0
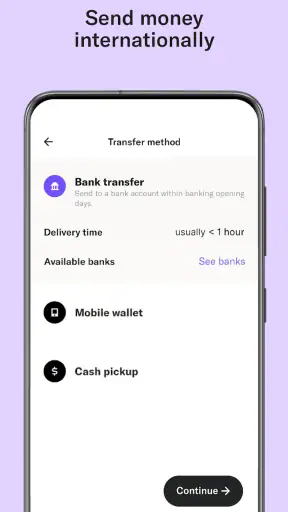
I tested MAJORITY as a finance app for people who want a practical way to manage everyday money in the United States without beginning with the usual banking paperwork. Its central appeal is easy to understand: it brings together a US account, a debit card, money transfers to family abroad, and tools connected with building credit. That combination makes it more focused than a general budgeting app, but also more dependent on whether those particular services match your situation.
MAJORITY is developed by MAJORITY USA, LLC and is available free of charge. That matters when judging its value: you can explore the app without paying an upfront purchase price. Free access does not automatically mean every possible service or transaction is free, so I would still read the terms shown during sign-up and before sending money. The useful distinction is that the app has no stated purchase cost to download, while the cost of individual financial actions should be checked at the moment you use them.
How MAJORITY fits into everyday money management
A finance app built around access and connection
In my experience, MAJORITY makes the most sense for someone who wants more than a simple spending tracker. The app is designed around having a US account and debit card, sending money home, staying connected with family, and working toward better credit habits. Those goals often sit in separate services, so having them presented in one place can reduce the need to move between several apps.
The account angle is especially relevant for people who find traditional banking applications difficult or unsuitable. MAJORITY presents itself as an option that does not require an SSN for the account experience described in its store summary. That can make the first step feel less intimidating for some users. It does not mean every person will have the same eligibility or that every financial feature works identically for everyone, so I would treat the sign-up flow as the final check rather than assuming the summary answers every personal circumstance.
The debit card gives the service a physical, everyday purpose. Instead of using the app only to look at balances, you can think of it as a place connected to routine spending. That is useful for groceries, transport, bills, or sending part of a paycheck to family. I would still keep an eye on the balance and transaction details, because convenience can make spending feel less deliberate when an app combines several money tasks in one account.
What the free price really tells you
The app itself is free, which lowers the barrier to trying it. There is no need to commit money simply to install it, and that makes it easier to compare the experience with your current bank or money-transfer service. For a person who is unsure whether a combined account and transfer app will fit their routine, this is a meaningful advantage.
However, I would not interpret “free” as a promise that every action has no charge. Financial apps can separate access costs from service costs, and transfers, card-related actions, or other account activity may have their own conditions. Since the confirmed price is free for the app, the sensible approach is to inspect the displayed cost before confirming a transaction, especially when sending money internationally or using a service for the first time.
This makes MAJORITY’s value fairly straightforward to judge. If you need its account, debit card, transfer tools, and credit-building direction, free access gives you a low-risk starting point. If you only need to record expenses, there are simpler budgeting tools. If your main goal is a traditional full-service bank relationship, you should compare the account details carefully instead of choosing based only on the download price.
A realistic use case for families and workers
Imagine someone who receives income in the United States, uses a debit card for local expenses, and regularly sends part of that money to relatives in another country. With a conventional setup, that person might use a bank for daily spending, a separate remittance service for family support, and another app or provider for credit education. MAJORITY is appealing because the workflow is more unified: check the available balance, handle ordinary spending, and begin a transfer from the same financial home.
The practical benefit is not just fewer icons on a phone. It can also make the money routine easier to remember. A user may be less likely to postpone a transfer when it is near the account used for everyday funds. At the same time, I would avoid sending money at the last second. Review the recipient, destination, amount, and displayed cost before confirming, and leave enough balance for upcoming card purchases rather than treating the entire account as available for remittance.
Credit-building needs patience and attention
The credit-building message is another reason someone might consider the app, but it should be approached as a long-term objective rather than an instant result. An app can help organize a financial routine, yet building credit depends on the specific product terms and on consistent behavior over time. I would read exactly how the credit-related feature works, what actions are expected, and which activity is actually reported or recognized before relying on it.
This is one of the less obvious trade-offs. A user may download MAJORITY expecting a quick credit improvement and feel disappointed if the process requires steady account management. The better mindset is to use the app as part of a broader routine: keep track of spending, avoid committing more than the balance supports, and review credit-related information rather than assuming the app alone will solve a credit history problem.
What the current app profile suggests
MAJORITY has reached over a million installs and holds a 4.7 average from roughly twenty-three thousand ratings, with about twelve thousand written reviews. Those figures suggest that the service has attracted a substantial audience and that many users find the concept useful. They are helpful signals, but they are not a substitute for checking whether the account structure and transfer options fit your own needs.
The app was released on April 26, 2019, and the current version is 5.14.0. It supports devices running iOS 9 or later, and its content rating is Everyone. I see that broad compatibility as helpful for people using older devices, although financial apps should still be kept updated whenever an update is available through the relevant app store. The age rating also makes the app approachable from a store perspective, but financial responsibility and account eligibility are separate questions.
Where MAJORITY is stronger than the usual alternatives
Compared with a basic expense tracker, MAJORITY offers a much more active financial role. A tracker can show where money went, but it does not replace an account or debit card. If your routine involves receiving and spending money, the app’s account-centered design is more useful than simply typing transactions into a budget category.
Compared with a standalone money-transfer service, the advantage is the connection to local spending and account management. You are not necessarily starting with a separate transfer destination every time. That can make recurring support for family feel more organized. The trade-off is that a dedicated remittance provider may be better for someone who compares exchange rates, delivery methods, recipient options, or transfer pricing very closely before each transaction.
Compared with a conventional bank, MAJORITY may feel more approachable for users looking for a US account without the standard SSN-centered starting point described in its summary. A traditional bank may still be preferable for someone who wants a broad branch network, a long-established set of account products, or a more conventional banking relationship. I would not choose one over the other purely because one app is free to download.
Small habits that make the app more useful
My first practical tip is to separate “money available now” from “money safe to spend.” If you use the same account for a planned family transfer and daily purchases, note the transfer amount before using the debit card. A quick balance check before shopping can prevent an avoidable shortfall and is more important than the convenience of having everything together.
My second tip is to treat every transfer preview as a checkpoint, not a formality. Verify the recipient details and the final amount shown before confirming. This is particularly important when you are sending money on a schedule, because a saved routine can encourage you to tap through too quickly. The app’s convenience is most valuable when paired with a deliberate review habit.
My third tip is to use the credit-building area as a learning tool rather than a promise. Keep notes about the actions you take and review your progress over time. If the app presents conditions or explanations, read them before assuming that ordinary debit-card use has the same effect as a dedicated credit product. This distinction can prevent unrealistic expectations.
A fourth useful habit is to compare the displayed transfer cost with your usual alternative before sending a larger amount. The app’s free download makes trying it easy, but the best value depends on the actual transaction you are about to make. For occasional transfers, convenience may matter most. For frequent or larger transfers, small differences in the final cost can matter more than having everything in one application.
Where the experience may create friction
The combined design is also the main source of possible confusion. An account, debit card, transfers, family communication, and credit-related tools serve different purposes. New users may need time to understand which balance belongs to which activity and which options are relevant to them. I would spend a few minutes exploring the navigation before making an important transfer, rather than assuming every screen works like a conventional bank app.
The no-SSN positioning can be valuable, but it should not be mistaken for a guarantee that every applicant or feature will be handled identically. Account services still involve identity and eligibility processes, and the sign-up experience is where you should confirm what applies to you. If your financial situation is unusual or you need a specific banking arrangement, ask the relevant questions before moving your main funds into the service.
Another limitation is focus. MAJORITY is not the obvious choice for someone who wants deep investment analysis, advanced household budgeting, or a wide collection of traditional banking products. Its appeal comes from a particular combination of access, spending, transfers, and credit direction. The more your needs move outside that combination, the more likely you are to prefer a specialist app or a conventional bank.
I would also avoid using any single app as the only place where you understand your finances. Keep important records, monitor account activity, and maintain a backup way to access essential money. That is sensible with any financial service, and it matters even more when one app becomes the center of your spending and family-transfer routine.
Who is most likely to get real value
MAJORITY is a strong candidate for people who need a US account and debit card, want to send money to family abroad, and appreciate a mobile-first approach. It may also suit users who are looking for a credit-building direction alongside ordinary account management. The free app price makes it reasonable to investigate without paying simply to begin.
It is particularly relevant when your needs overlap. Someone who only wants a debit card may find the transfer and credit sections unnecessary. Someone who only wants to send money internationally may get better results by comparing specialist services. The greatest value appears when one person regularly needs local spending, family support, and a simpler path into financial management.
I would be more cautious if you need highly specialized banking features, extensive in-person support, or a very detailed comparison of international transfer pricing. In those cases, a traditional bank or dedicated transfer provider may be a better primary choice. You can still consider MAJORITY as a secondary tool, but I would not force it into a role it was not designed to fill.
My verdict after weighing the value
MAJORITY delivers a clear kind of value: it offers free access to an app centered on a US account, debit card use, sending money home, and credit-building goals. Its strongest quality is the way those needs are brought together for users whose financial lives cross borders. The app is easier to justify when you will actively use several of those functions, not merely download it because the price is zero.
My recommendation is to try it if you want that combination and are willing to inspect the terms of each financial action. Start with a small, familiar workflow, learn where balances and transfer details appear, and compare the final cost of important transactions with your current alternative. That approach lets you judge the service on practical value rather than on the store rating alone.
I would skip it as a primary financial app if you need a full traditional banking ecosystem, advanced money analysis, or a specialist remittance experience. For everyone else, especially users seeking a more accessible mobile account with family-transfer and credit-building goals, MAJORITY is worth a careful look. Its best value comes from matching several everyday needs in one place while keeping the initial app cost free.
FAQ
What is MAJORITY, and who is the mobile banking service designed for?
MAJORITY is a mobile banking service designed primarily for immigrants, newcomers, and people who need a practical way to manage everyday finances in the United States. After reviewing the app, its main focus is convenient money management through a mobile account, debit card access, direct deposit features, international calling options, and selected remittance services. Availability and benefits may depend on your location, eligibility, and the current plan offered.
What documents are required to open a MAJORITY account?
To register, users generally need to provide personal information and complete an identity-verification process required for financial services. Depending on your circumstances, the app may request details such as your legal name, date of birth, address, phone number, and an accepted identification document. Requirements can vary, so you should carefully follow the in-app instructions and make sure all information matches your official documents.
Does MAJORITY charge monthly fees or other service costs?
MAJORITY may operate with a membership or subscription fee, depending on the plan and offer available when you sign up. Additional charges can apply to certain services, such as cash deposits, out-of-network ATM usage, international transfers, or optional features. Before downloading or subscribing, review the current pricing page and account agreement because fees, limits, promotions, and included benefits may change over time.
Can I receive my paycheck or government benefits through MAJORITY?
The app supports direct deposit functionality for eligible users, allowing qualifying paychecks or certain government payments to be deposited into the account. Setup normally requires providing the correct account and routing information to your employer or payment provider. Deposit timing is not always controlled by MAJORITY and may depend on the sender, processing schedules, weekends, holidays, and verification requirements.
Is MAJORITY a bank, and is my money protected?
MAJORITY provides mobile financial services through partner financial institutions rather than functioning as a traditional bank with physical branches. Depending on the specific account structure, eligible balances may receive protection through applicable deposit insurance provided by the partner institution, subject to legal limits and conditions. Read the account disclosures carefully, since not every service, balance, or transaction is necessarily covered in the same way.


